
Administrivia.
Wheatie Wisdom. If you bring snacks, bring enough for everyone. No running with scissors. No food fights. AI stuff posted, requires a link. Please use spoiler, for longer posts. Wolf Speak. No obnoxious behavior towards fellow QTreeper(s). Freedom of Speech is honored here QTree. But Do Know, every poster, IS personally responsible for what they post.
APMEX https://www.apmex.com Bitcoin https://www.bitcoin.com/
Prices pulled last evening. Gold $4,156.60 Silver $61.14 Bitcoin $84,600
Seems like such an obvious solution.
Elon blasted out the obvious…
Until we elect a conservative majority, we’ll…
Stuff…
OK so I was bouncing around YT and saw below video. Being a geezer, thought, what the hell…
- Not in the market for a new vehicle until, I hope 2028.
15:13
—
Then I wondered, would geezer car insurance rates go down. So I asked Grok.
- Yea, grok would have no conflict of interest here.
Grok
71yo driver. No accidents OR moving violations since 1975. Texarkana, TX. Typical insurance rates for a Tesla Y FSD?
Typical full-coverage rates for a Tesla Model Y in Texarkana, TX, for a 71-year-old with an exceptionally clean record (no accidents or moving violations since 1975) are roughly $180–$320 per month ($2,200–$3,800 per year), depending on exact coverage, deductibles, mileage, credit, and insurer. Liability-only is substantially lower. These are estimates based on 2025–2026 published averages and comparisons; actual quotes vary and require personalized shopping.
Key Benchmarks
- Texas Model Y averages (full coverage, typical middle-aged clean-record driver, 100/300/100 limits + $500 deductibles): Around $4,169 per year / ~$347 per month. Liability-only (higher limits) averages closer to $1,495 per year. insurance.com
- National Model Y full-coverage averages: Often $3,000–$4,600 per year (~$250–$380/month) for similar profiles, with some sources lower for safer/older drivers. insurance.com
- Age effects: Rates for seniors in Texas rise modestly after ~65–70. A typical 70-year-old pays about 8% more than a 65-year-old for full coverage on an average vehicle (e.g., statewide senior full-coverage averages near $2,800–$3,000/year). Tesla premiums run higher due to vehicle value, battery/repair costs, and parts. Clean multi-decade records and mature-driver discounts help offset this. carinsurance.com
- Texarkana specifically: Lower than major Texas metros (DFW/Houston averages for Model Y clean-record full coverage often $220–$400/month). Overall city auto averages for full coverage are frequently in the $170–$180/month range for typical cars—noticeably below the Texas statewide average—due to lower urban density/claim frequency. insurify.com
Tesla Insurance Advantage (Available in Texas)Tesla Insurance prices primarily on the vehicle’s Safety Score (and mileage/garaging) rather than age or credit score, which can benefit a very safe senior driver. It also offers an FSD (Supervised) usage benefit/discount in Texas (up to ~10% on eligible coverages for ≥50% of miles with FSD engaged; higher usage can produce larger effective savings in examples).
Example order-page estimates (Austin-area Model Y context, not Texarkana-specific): ~$205/month without heavy FSD use vs. ~$148/month with high FSD usage. Real rates depend on your Safety Score, ZIP, and coverage. High scores can produce competitive or lower-than-traditional rates.
Factors That Help or Hurt Your Rate
- Helpful: 50+ years clean record, potential low annual mileage, mature/defensive driving course (common 5–10% discount for 55+ in Texas), multi-policy bundling, higher deductibles, Tesla’s advanced safety features, and strong Safety Score/FSD usage with Tesla Insurance.
- Higher cost drivers: Newer/higher-trim Model Y, low deductibles, high mileage, urban ZIP nuances, or comprehensive coverage in hail-prone areas.
- Company variation is large: In Texas Model Y data, full-coverage quotes have ranged widely (e.g., State Farm or Incline often lower; others substantially higher). USAA can be competitive if eligible. insurance.com
Practical AdviceShop quotes from Tesla Insurance, State Farm, GEICO, Progressive, Nationwide, local/independent agents, and others (or comparison sites). Provide your exact ZIP, model year/trim, desired limits/deductibles, annual mileage, and any other vehicles/homeowners policy. Complete a Texas-approved mature driver course if you haven’t recently. Rates are not guaranteed and change with market conditions, claims experience, and underwriting.These figures assume standard full coverage on a typical recent Model Y; liability-only or higher/lower limits will differ materially. Get multiple personalized quotes for the most accurate picture.
Me. Interesting it appears some insurance company rates go down with increased FSD engaged. Minor plug for Tesla insurance. 🙂
Maintenance appears to be minimal, as compared to ICE.
EVs still have a ways to go.
Are EV fires still an issue OR was that mainly non-Tesla EV fires for the most part. Based on Grok search, does not appear to be a significant issue. I spose, keep the Tesla out of water and hope it doesn’t catch on fire for any reason.
Cold weather issues. Charge time. Charge limits. Increase charge drain. Long distance travel on holidays likely long wait times to charge EVs.
Then I looked at Tesla weight Vs my Ram and Grand Cherokee L. Ram 25% heavier. Grand Cherokee L about the same. So much for the EVs are too heavy hype.
Tire prices comparable to what I buy these days. Maintenance appears to be much less than ICE.
Charging station availability on demand, likely my biggest concern. 2028 charging station availability may not be an issue.
So much for the Tesla rabbit hole deep dive of sorts.
—
This looks interesting.
Elon Musk Makes A Move On The Banks
When Elon Musk took over Twitter, fired four out of five employees, and rebranded it X (just because he thought it sounded cool), the talking heads predicted doom for the company. The opposite happened. It is now one of the most popular sources of news in the world, and a major delivery system for what social media is supposed to be.
He always had more in mind. He explained at the outset that he wanted to turn X into the “everything app.” I winced when I heard those words. As someone who worked in web development for years, I learned to regard every promise of a “one-stop shop” to be foolish. It never happens. Best to pick one thing you do well and stick with it.
To my own amazement, X is indeed taking steps toward being the Everything App. Not yet, of course, but the advent of his X Money platform is major and serious. It is being rolled out gradually to premium members. Under the new content-creators payout program, people are paid within the app and invited to use the service for transferring money.
Described thusly, it would seem to be another version of Zelle or Venmo and therefore not that much to notice, much less celebrate. But when you look at the details of what X Money is doing, another reality emerges. It would appear that this app is making a move on the banks themselves.
The evidence is on the app now. It offers a way to link your paycheck to X Money to enjoy a quicker payout than if your paycheck flows to your bank account. Speed is one thing, and a good thing, but why else would you do this?
The key comes in the details which have not been advertised (Musk doesn’t like old-style marketing). These are not regular dormant cash accounts like you get in a regular checking account. They pay a return. Not just any return. The return is higher than you would otherwise get in a normal money market.
For now the Annual Percent Yield (APY) is an eye-popping 6 percent as an initial customer-acquisition rate.
Not only that, the X Money card that comes digitally with the service (and physically on the ask) offers fully 3 percent cash back.
A high rate plus instant peer-to-peer transmission, a metal Visa card with 3 percent cash back, and early direct deposit is meant to pull balances and daily activity onto the platform.
What you notice from these terms is that this goes way beyond a mere money-transmission service. What’s being provided here, with quick and easy signups, is a highly lucrative vehicle for serious investment. Put your cash in and have it earn 6 percent. That beats inflation. With 3 percent cash back, you are way ahead of the game. That is reason enough to switch.
As a user I immediately found myself in a bind. Initially I thought I would enjoy spending my X Money on groceries and movie tickets or something along those lines. But with this level of earning power, I will lose money if I do that. I would be forgoing the return from the money held. Better to use the cash in my bank or my credit card that also pays 3 percent cash back.
The calculation here favors keeping the money in X Money, not spending it. Indeed, the calculator favors moving cash from banks into X Money and earning the return. To be sure, that 6 percent could change in a year or two or three. It would be up to how the app is managed.
Meanwhile, do you understand what this means? It means an actual reward for … saving money! Imagine that. Cash that earns a return on an app that allows peer-to-peer transfer at zero cost. This is disruptive innovation of the sort we’ve come to expect from this man and his companies.
Elon has designated the X Money app for now to be a loss leader in direct revenue but a huge investment in becoming what he likely thinks it can be in the long run: an actual option to the banks.
There might even be more afoot here. The banking rails themselves are provided by Cross River Bank. Founded in 2008, the bank carved out a special niche in working with new digital companies that focus on in-app service provision and edgier products like cryptocurrency. It is FDIC-insured but eschews traditional banking in favor of innovation. Even with its smaller capitalization, it is an ideal partner for a disruptive technology like X Money.
Recall too that Elon Musk was one of the founders of PayPal. It was started with a high hope of developing a new form of money transmission and even a new form of money. It eventually found itself regulated out of that vision to become what it is today, which is a highly valued means of payment for the digital age.
X Money seems to learn from mistakes made in those days to build out fully banking services from the very foundation. With the inclusion of crypto as part of the banking rails, we can easily imagine a future in which X Money integrates with a service like Coinbase to move money from dollars to crypto and back again.
One thing that is notable to me is the effortlessness of the signups and verifications. The developers have learned that customers recoil at too many screens, too much language, too many aggressive demands for passwords and accounts. They are using the latest technology to make signups and management extremely easy and clean.
That said, X Money does of course comply with all the arduous federal regulations concerning Know Your Customer laws and tax-reporting requirements. This is by no means an app that places a premium on your privacy. Even to make it work requires government IDs and 3D facial scans from our phone. I despise all of that while also understanding that this is the price any financial entrepreneur pays to make anything innovative these days. X Money is compliant across the board, which, from my point of view, is unavoidably regrettable.
It’s entirely possible that Elon has a big vision for this platform that he has not yet shared. Indeed, I’m struck by how much of the system that he has built so far has not been advertised at all. It’s extremely interesting how the rollout is going. The app presents direct information to the customer screen by screen, the pitch, the conditions, the advantages. Normal advertising speaks to the masses; Elon’s way is to speak to the individual user. It’s very different.
We can imagine two polar opposite futures with this new service.
Optimistically, it becomes the innovator of a new form of money and monetary services that eventually replaces paper money and even the dollar.
Remember that the app is global. What if the assets of X and other companies emerge as the asset baking of a new form of currency?
Pessimistically, X Money becomes just another new layer of the emergent financial control grid that spies on us and even worse: the integration of money and social media reminds one of China’s Social Credit System. This future sometimes feels baked into the technologies we use and the deep relationship of tech companies and the government.
Which will it be? We do not know. But from what I can see, there is a strong rationale for expecting this platform to be a major player and going concern in the future world of money and finance.
https://www.zerohedge.com/technology/elon-musk-makes-move-banks
—
Have a laugh…
1:02
—
Worthy rerun. Hilarious back and forth between 84yo guy and traffic judge.
Yes. It was posted late last Saturday evening. Still funny.
2:48
—
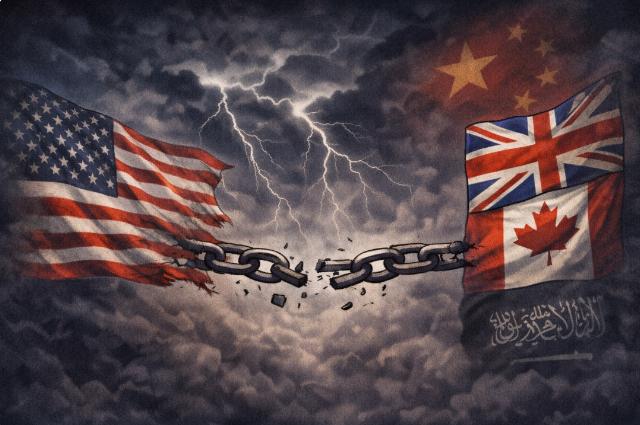
Grateful our ancestors broke the British chains, again, and again…
Thankfully, Trump is finishing off the Brits, Canucks… Along with NATO. Ideally UN.
—
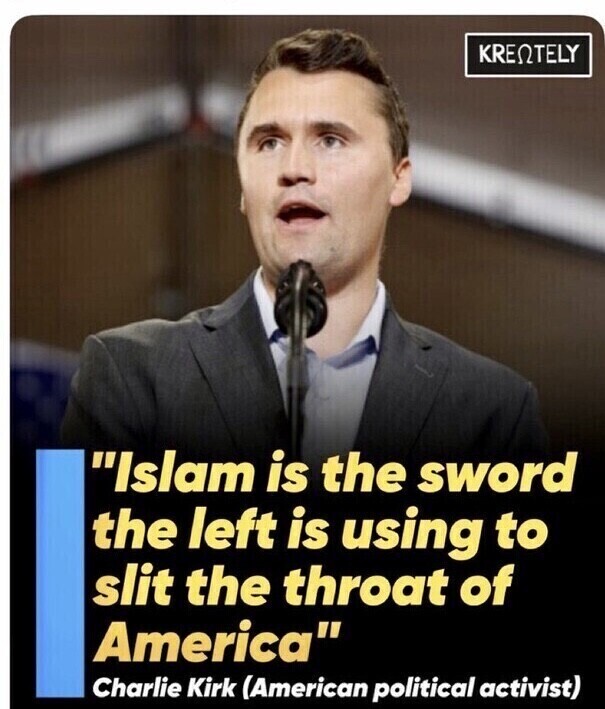
Charlie called out the islami cancer…
—
Stay The Course. Trust Trump. Remember…
Never, Ever, forget what they did to us.
Celebrate America, Everyday!!!
Relax, It’s Saturday.
Night crew, your nickel.
KK


Almost an hour and no comments.
Explain yourselves, Q-tree branch dwellers.
Sir, I was reading the content, sir. 🫡
I got an “article rating” in a while ago.
Two humorous videos, and very interesting research on self-driving cars. The video about the elderly having more independence and being safer on the road is something I never expected to see.
And Elon is always coming up with something unprecedented.
Need to start talking up that $5,000 dividend check to every American, even to loser d-Rats, if they vote Team Red.
They’ll be sweatin’, walking into the voting booth.
They could really use that $5,000… but Orange Man Bad!!!
On the one hand, $5,000… on the other hand, Orange Man… bad?
$5,000… Orange Man… maybe not so bad?
$5,000… Orange Man good… at least good enough!
I’ll take that $5,000 Orange Man! 😂
FBI Records Reveal Trump Gunman’s Redacted Chat Thread, Drone Photos
“In his words, Somalia has a 98% unemployment rate, “but they’re very good at ripping us off.” ”
______________
Hmmm… according to Brave Si, Somalia also has a 99% to 99.9% islami rate.
Coincidence?
I think not! 🤣
They never stop…
Natalie Winters:
Sean Parker is a terrorist, working with foreign adversaries against America.
I have always doubted that all military ballots got counted. Supposedly they could still get counted after election day, but usually by that time things have already been decided. And with all the cheating we know about, I would bet that they sometimes haven’t been counted at all. I’m glad Sec. Hegseth is doing this.
I keep wondering why we need all these foreign countries to come in and build and then own companies in America.
Why can’t Americans invest in America, and American infrastructure?
Whatever deals and tax breaks and credits and other incentives they’re giving to foreign countries and companies, why not give those same opportunities to Americans?
Why can’t Americans buy into this explosion of growth? Why aren’t there investment vehicles that Americans buy, just like stocks?
Why can’t Americans invest in the ‘enhanced oil recovery project’, and get tax-free 30% to 50% dividends paid monthly, for life?
Why does only BIG (foreign) OIL get to play?
“Even to make it work requires government IDs and 3D facial scans from our phone.”
____________
Nope! 😁
I was thinking about it, considering the possibilities, right up to then!